Double Tax Treaties in Luxembourg
Overview of Luxembourg's double tax treaties, including those with the UAE, Germany, the UK and the USA, and how they help avoid double taxation. Ask us.
Luxembourg has concluded 88 double tax treaties in force (July 2026), and 6 more are signed but not yet in force. A Convention for the avoidance of double taxation is advantageous for foreign investors from that country who want to open a business in Luxembourg or vice versa. One of our company registration specialists in Luxembourg can provide support and guidance to entrepreneurs from abroad who want to start and register a company in Luxembourg. If you want to open a bank account in Luxembourg, we can offer assistance.
The provisions of a double tax treaty
The model used for the double tax avoidance agreements is in line with the provisions of the Organization of Economic Cooperation and Development. The most important goal of a double taxation treaty is to eliminate double taxation for the same individual or same legal entity. This implies that the Contracting States decide which one will levy a certain tax on the income produced therein.
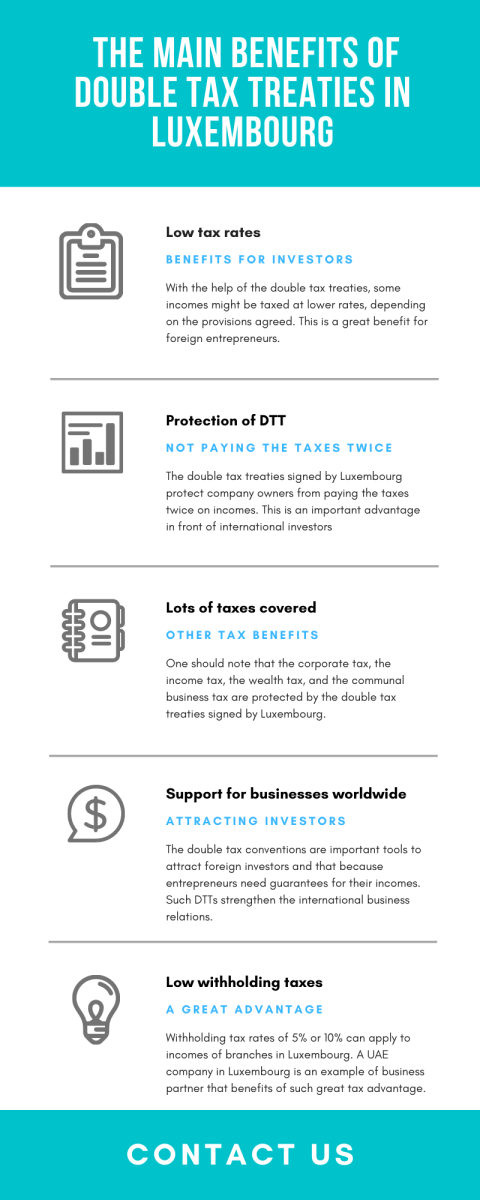
The withholding taxes on dividends, royalties and capital gains are targeted in all double tax treaties. While both countries impose a normal rate for these types of income, under an agreement of this type the rate will be reduced and in some cases will be even eliminated completely. The types of taxes usually covered by a double tax treaty include the corporate tax, the income tax, the wealth tax, the communal business tax and others. Special provisions within these treaties allow for the prevention of tax discrimination and also for the prevention of tax evasion. Special rules are in place for the exchange of information between the Contracting States. Here is an infographic with information about the main benefits of double tax treaties signed by Luxembourg:
Double tax treaties signed by Luxembourg
Luxembourg has signed double tax treaties with the following countries: Armenia, Austria, Azerbaijan, Bahrain, Barbados, Belgium, Brazil, Bulgaria, Canada, China, the Czech Republic, Denmark, Estonia, Finland, France, Georgia, Germany, Greece, Guernsey, Hong Kong, Hungary, Iceland, India, Indonesia, Ireland, Isle of Man, Israel, Italy, Japan, Jersey, Kazakhstan Laos, Latvia, Liechtenstein, Lithuania, Macedonia, Malaysia, Malta, Mauritius, Mexico, Moldova, Monaco, Morocco, the Netherlands, Norway, Panama, Portugal, Qatar, Romania, Russia, San Marino, Saudi Arabia, Seychelles, Singapore, Slovakia, Slovenia, South Africa, South Korea, Spain, Sri Lanka, Sweden, Switzerland, Taiwan, Tajikistan, Thailand, Trinidad & Tobago, Tunisia, Turkey, United Kingdom, United Arab Emirates, USA, Uzbekistan, Vietnam.
Treaties signed but not yet in force: Argentina, Cabo Verde, Colombia, Ghana, Kuwait and Oman; Kyrgyzstan is initialled only, and Chile, Egypt, Mali, New Zealand and Pakistan are under negotiation. Albania, Andorra, Botswana, Brunei, Croatia, Cyprus, Ethiopia, Kosovo, Montenegro, Poland, Rwanda, Senegal, Serbia, Ukraine and Uruguay also have treaties in force.
Depending on the business you want to develop in Luxembourg, you must choose the right structure. In addition to the registration formalities of a company, we advise you to contact our accounting firm in Luxembourg in order to benefit from complete services. Audits, bookkeeping, payroll, and submission of annual financial statements are some important procedures that tend to a company’s accounting. Therefore, we are waiting for you to contact us and benefit from personalized offers and full support.
What are the provisions of Luxembourg – UAE treaty?
The economic collaboration between Luxembourg and the UAE dates for many years and a double taxation treaty signed by both countries strengthened the business relations in varied sectors of interest. The agreement applies to the wealth tax, income tax, communal tax imposed on commercial profits and the corporate tax in the case of Luxembourg. As for the UAE, the DTT covers the corporate and personal income tax. More than that, it is important to know that there is no withholding tax imposed on interests, royalties, and dividends in the case of the UAE.
A withholding tax of 15% rate is not applicable if the parent company established in Luxembourg is a resident company in UAE. Branches of companies from the UAE that are established in Luxembourg might be subject to a 5% or 10% withholding tax rate under particular conditions. All the provisions of the double taxation agreement signed between Luxembourg and the UAE can be explained by one of our company formation agents in Luxembourg who can also help you register a company in Luxembourg.
The provisions of Luxembourg – Germany DTT
The protection of business collaborators and economic partners is important for Luxembourg, and a double taxation treaty first signed in 1958 and replaced by a new treaty signed on 23 April 2012 (applicable since 2014, amended by a 2023 protocol) met a series of modifications and updates in terms of provisions. Among these, the dividend withholding tax is reduced from the domestic 15% to 5% for companies holding at least 10% (15% otherwise) if the company is a German resident. The agreement signed by Luxembourg and Germany also mentions the protection of the corporate tax, the wealth tax, and the income tax that is applicable to resident companies of both states. More details and information about the double taxation treaty signed by Luxembourg and Germany can be obtained from one of our specialists. You can also ask us about how to set up a fund or about how to open a SARL in Luxembourg.
Luxembourg – UK double tax treaty
The capital gains tax, the corporate tax, and the income tax (and, for Luxembourg, the wealth tax and municipal business tax) are protected by the double tax treaty signed by Luxembourg and UK, for British companies. We mention that UK companies with establishments in Luxembourg (offices, factories, branches, construction sites; a subsidiary is not in itself a permanent establishment) will only be taxed in Luxembourg for the profits generated in this country. The same thing is available to Luxembourg companies registered in the United Kingdom. Furthermore, the provisions of the agreement signed by Luxembourg and UK mention that the royalties which need to be paid to a company from Luxembourg are exempt from withholding tax (0%) under the new treaty applicable since 2024. More aspects related to the provisions of the double tax treaty signed by Luxembourg and the UK can be detailed by one of our company formation representatives in Luxembourg.
Luxembourg and UK have agreed upon and signed a double taxation treaty for taxes on income and property. The original 1967 convention was replaced by a new treaty signed on 7 June 2022, applicable in Luxembourg from 1 January 2024 and it is useful for the prevention of double taxation of individuals doing business and earning income in the two countries, as well as for the protection against fiscal evasion.
The convention sets forth the manner of taxation, taxes covered, it refers to multiple types of income and it also describes the rules for exchange of information and mutual collection. Our Luxembourg company registration agents can help you understand the implications of this convention, if you are a UKforeign investor in Luxembourg.
Luxembourg – USA double tax treaty
The taxes covered by the double taxation treaty between the US and Luxembourg are as follows:
- for Luxembourg: the income taxes on individuals and companies, the taxes on the director’s fees, the communal tax on commercial profits, the wealth tax and the communal tax on invested capital and land;
- for the United States: the federal income tax, including surtax.
The treaty also applies to similar taxes or taxes imposed in addition to or in place of the aforementioned taxes. The two countries must notify one another, if any changes occur in their taxation laws. Our Luxembourg company registration agents can give you details about the taxes in Luxembourg applicable for companies and individuals.
For the purpose of the convention, an enterprise in one of the two states is a legal entity created in that state and organized under the laws of the state. The term “permanent establishment” can refer to a branch in Luxembourg or in the USA, a place of management, an office, factory or workshop. A resident or company in one of the contracting states is taxed as per the income produced in that state. The treaty for the avoidance of double taxation on income is an effort not only to eliminate the unnecessary payment of the same type of taxes, but also an agreement that encourages international trade and investment in Luxembourg and establishes a series of procedures for the mutual assistance of the tax authorities of the two countries
Short facts about taxation in Luxembourg
Luxembourg is an appealing business hub that offers great conditions in terms of taxation to international investors. For instance, companies with less than EUR 175,000 taxable income, the corporate income tax of 14% will apply. For companies with taxable incomes between EUR 175,000 and 200,000 must pay EUR 24,500 and 30% of the tax base above EUR 175,000. The solidary surtax of a 7% rate is levied on the corporate income tax of all companies (16% rate above EUR 200,000). The municipal income tax of 6.75% is applicable in Luxembourg City, but it varies in each municipality. When it comes to VAT, this one of the lowest among the European countries and it is established at a 17% rate for most taxable goods and services. A reduced VAT tax of 14% rate applies to mineral oils, printed advertising materials, credit administration and more. As for the 8% VAT rate, this is applicable to gas and electricity, firewood, hairdressing and minor repairs of clothing, shoes and leather goods, among others. The VAT rate of 3% applies to foodstuff, pharmaceutical products, books, restaurant services (excluding alcohol), children's clothing and footwear, etc. Below you can find some interesting information and facts about the economy and the investments in Luxembourg:
- • EUR 164,806 million was the FDI stock registered in Luxembourg in 2018;
- • The World Bank discontinued its Doing Business report in 2021; its 2019 edition placed Luxembourg on 66th position among 190 worldwide economies.
- • The government in Luxembourg sustains foreign investments of any kind, among which, the ones in the financial services, biotechnology, and other innovative industries;
- • In the last WEF Global Competitiveness Index (2019), Luxembourg ranked 18th.
Those interested in more details about the double tax treaties signed by Luxembourg with countries worldwide should address their inquiries to our team. If you are a foreign investor from one of these countries or if you simply want to know more about taxes in Luxembourg and other issues concerning investments you can get in touch with our company registration agents in Luxembourg.
Taxation of holding companies in Luxembourg
The taxation of holding companies established in Luxembourg is attentively measured by entrepreneurs who want to be prepared from this point of view. There are no withholding taxes imposed on holding companies registered in Luxembourg on dividends paid to a parent holding at least 10% (or a participation acquired for at least EUR 1.2 million) for at least 12 months. Also, the property transfers of holding companies registered in Luxembourg are not levied. It is important to note that holding companies in Luxembourg are protected by the double taxation treaties signed with countries worldwide.
Taxation of investment funds in Luxembourg
Hedge funds are preferred by international investors due to simple incorporation and a series of other advantages. The double taxation treaties in Luxembourg play a major role for investment funds in this country and especially for hedge funds for which owners do not need to pay a wealth or income tax. We remind that Luxembourg signed a series of double taxation treaties with countries like Austria, France, Liechtenstein, Canada, USA, Malta, Denmark, China, Italy, Germany, Bulgaria, Slovenia, Spain, Indonesia, Finland, or Monaco. If you need more details about the taxation of investment funds in Luxembourg and a specific double tax treaty in Luxembourg, feel free to get in touch with our company formation representatives in this country.
If you want to open a special limited partnership in Luxembourg, our company formation specialists can help you.
FAQ about double tax treaties in Luxembourg
The elimination of double taxation is the main purpose of the treaties signed by Luxembourg wide numerous countries worldwide. Companies are also protected against fiscal evasion.
The income tax, the corporate tax, and the wealth tax are protected in Luxembourg, thanks to the double taxation agreements signed in this sense. The provisions of DTTs can be explained by one of our specialists in company formation in Luxembourg.
Yes, the DTTs signed by Luxembourg mention the taxation of royalties, capital gains, and dividends. Reduced rates might apply under certain conditions.
Branches, offices, factories, workshops and construction sites (a subsidiary is not by itself a permanent establishment) are considered permanent establishments in Luxembourg and are mentioned by the double tax treaties in Luxembourg.
Yes, the double taxation treaties signed by Luxembourg also mention the incomes of natural persons who live in Luxembourg. We remind that residents in Luxembourg are taxed on their worldwide income, with treaty relief for foreign income.
In the case of USA, the surtax and other federal incomes are protected by the double tax treaty signed by Luxembourg with USA. In the case of Luxembourg, the income tax, capital gains tax, and other taxes are stipulated by the same agreement.
If one of the participant countries that signed a double tax treaty with Luxembourg wants to change or to improve specific provisions, the representatives must notify the other party before any move. The protocols of the agreement can be renewed from time to time.
Yes, subsidiaries and branches in Luxembourg are protected by the double taxation agreements signed by Luxembourg with worldwide countries. Doing business in Luxembourg as a foreign investor is quite beneficial from a taxation point of view.
Yes, the double taxation treaties are quite beneficial for foreign companies in Luxembourg. The tax regime is already advantageous, as Luxembourg is one of the most important financial centers in the world.
Yes, the registration for taxation purposes in Luxembourg is not a complicated process as long as you benefit from complete support and guidance offered by a team of specialists. We have a dedicated team of advisors with experience in taxation who can also tell you more about any double tax treaty in Luxembourg.
Daniel Milano, Financial Consultant Sigtax · 2 October 2026